A homeowner asked me a question recently that I’ve probably been asked thousands of times over the years.
“What do you think my house is worth?”
It’s a perfectly reasonable question. It’s also one of those questions appraisers can make unnecessarily irritating by answering with another question.
Worth for what?
I know. Nobody wants to hear that.
If you’re thinking about selling your house, you want a number. If you’re getting divorced, settling an estate, reviewing your insurance or trying to understand what you’ve built over the years, you probably still want a number.
The problem is that “value” isn’t always one number, because sometimes we’re asking entirely different questions about the same property.
The House Hasn’t Changed. The Question Has.
Imagine a home in the foothills on five acres.
It has a 2,500-square-foot house, a detached garage, a workshop, a well and septic system, some mature trees and enough space between the house and the road that you can barely see it as you drive past.
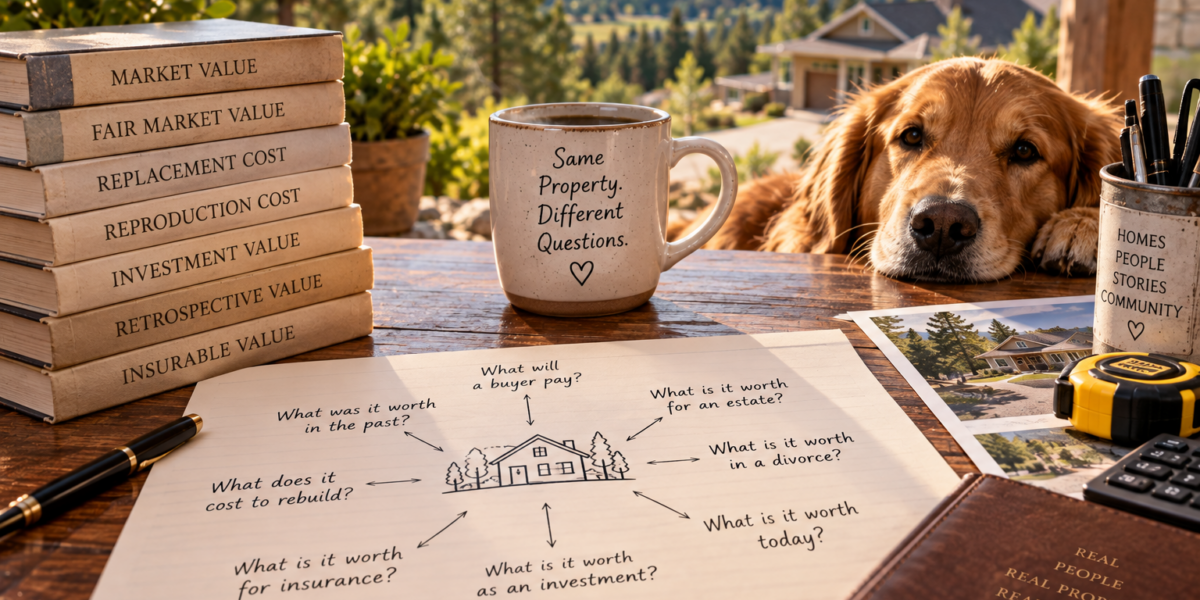
Ask a buyer what it’s worth and they’re thinking about what they would pay for it. Ask the owner what it’s worth and they may be thinking about what they could sell it for. Ask an insurance company what it would cost to replace the house after a fire and we’re suddenly talking about construction costs rather than what a buyer would pay for the property.
Ask what it was worth when Dad passed away three years ago and we’ve moved the entire valuation question backward in time. Ask an investor what it’s worth and income may become part of the conversation. Same property. Different questions. Potentially different answers.
That’s why one of the first things an appraiser needs to understand isn’t simply What property are we appraising? It’s what question are we trying to answer?
Market Value Is Probably the Number You Were Thinking About
When most homeowners ask what their house is worth, they’re usually thinking about some version of market value: what would this property reasonably sell for in the marketplace?
That sounds simple enough, and for an ordinary conversation it usually is.
Appraisal work gets more precise because different assignments can require specific definitions of value. “Market value” and “fair market value,” for example, are phrases people often use as though they mean exactly the same thing. Depending on the purpose of the appraisal, the applicable definition may come from a lender, government agency, tax authority, court, regulation or another source.
That distinction matters to appraisers. It probably doesn’t need to dominate your dinner conversation.
The useful idea for a homeowner is simpler: before we can answer what something is worth, we need to know what kind of value we’re being asked to develop and why.
What Buyers Will Pay Isn’t What It Costs to Build
This distinction becomes especially important with insurance. Suppose our foothill property would sell today for $900,000. That does not mean it would cost $900,000 to rebuild the house if it were destroyed.
The market price includes land. It reflects location, supply and demand, buyer preferences and all the things happening in the local real estate market. Reconstruction asks a different question: what would it cost to recreate the improvements?
Those two numbers don’t have to match.
A modest house can sit on extremely valuable land. A very expensive house can sit in a location where buyers won’t pay anything close to what it would cost to build that house again.
I’ve seen homeowners stumble over this because the numbers seem as though they should be related. Sometimes they are. They just aren’t answering the same question.
Then There Is Cost
This is another place where everyday language and appraisal language can wander apart.
You spend $100,000 remodeling your kitchen. The cost is $100,000. We have receipts. Does that mean your house is now worth $100,000 more? Maybe, but probably not simply because that’s what you spent.
Buyers might love the kitchen and pay considerably more for the house because of its overall condition and appeal. They might recognize some portion of that expenditure in the price. Or you may have selected materials and features you adore that the next buyer considers perfectly nice but not worth paying an additional $100,000 to obtain.
Cost tells us what you spent. Market value asks how the market responds to what you created. Those are related ideas, but they aren’t interchangeable.
Replacement and Reproduction Aren’t Quite the Same Either
Imagine we’re appraising a hundred-year-old house. It has plaster walls, old-growth wood trim, custom windows and craftsmanship that would be extremely expensive to duplicate exactly today.
One question might be: what would it cost to build a house that provides similar function and utility using modern materials and construction? Another might ask what it would cost to reproduce the original structure much more closely. Those aren’t necessarily the same number.
This distinction can matter with unusual, historic or highly customized properties where duplicating exactly what exists may be very different from replacing its usefulness with a modern equivalent.
Then we have another problem. The house isn’t new. Parts of it have worn out. Some features may be dated. Its design may not fit the way today’s buyers prefer to live. Something outside the property may have changed around it.
That’s where depreciation enters the conversation. Suddenly our innocent little question, What’s my house worth?, has wandered into an appraisal textbook. I’ll rescue you now.
Sometimes the Property Is About the Income
Most people buying a typical single-family home aren’t sitting at the kitchen table calculating the return produced by the third bedroom. They want somewhere to live.
But some real estate is purchased primarily because of the income it can generate. Rental properties are an obvious example. Now the questions change again.
What rent can the property produce? What expenses come with owning it? How reliable is that income? What return are investors expecting from competing investments?
An appraiser analyzing an income-producing property may look at how investors convert that anticipated income into value. The walls didn’t change. The economic lens did.
And Sometimes We Have to Ask the Question in the Past Tense
This is the strange world of retrospective appraisal. The house may be worth $850,000 today, but an estate needs to know what it was worth when Dad passed away in 2021. Today’s number doesn’t answer that question.
We have to go back to the relevant effective date and examine the market that existed then. The property may have been worth less. It may have been worth more. Time itself becomes part of the assignment.
This is one reason an appraisal should never really be reduced to a naked number. A value conclusion belongs to a particular property, under a particular definition of value, for a particular purpose and as of a particular date.
Take away those things and the number begins losing its meaning.
This Is Why Two Numbers Don’t Always Contradict Each Other
Suppose you have an appraisal saying $825,000. Your insurance documents indicate a reconstruction cost of $575,000. Zillow says $847,000. An old appraisal says the property was worth $690,000 three years ago.
Your neighbor tells you it would cost more than a million dollars to build your house and buy the land today. At first glance, somebody appears to be wrong. Maybe somebody is.
But before deciding that, I’d want to know what each number is supposed to represent.
The $825,000 might be an opinion of current market value. The $575,000 might relate to reconstructing the improvements and exclude land. The $690,000 might be a retrospective opinion from a different market. Zillow is producing an automated estimate using its own model and available data. Your neighbor may be combining land acquisition and new construction costs.
Five numbers can describe one property without all five answering the same question. That’s not appraisal magic. They’re measuring different things.
So, What Is My House Worth?
Now we’re back where we started. If you call me and ask what your house is worth, I may still annoy you by asking why you need to know. Not because appraisers enjoy making simple things complicated. We already have plenty of other ways to accomplish that.
I’m asking because the purpose tells us what we’re actually trying to measure. Are you selling it? Settling an estate? Going through a divorce? Trying to understand reconstruction cost for insurance? Evaluating an investment? Establishing value as of some earlier date?
Once we know that, the question gets much easier to answer.
As an aside, if you know an appraiser casually and ask, “Hey, what do you think my house is worth?” don’t be offended if they won’t give you a number. If you’re asking because you know they’re an appraiser, what feels like a casual opinion can quickly become a professional one. Appraisers have standards governing the value opinions they provide, and your friend may not be willing to throw out a number without doing the work necessary to support it. Even the seemingly harmless, “Just give me a ballpark, my friend,” isn’t quite as harmless for the appraiser as it sounds.
A house can be a home, an asset, an investment, an inheritance, collateral, something to insure or something two people now have to divide. Sometimes it manages to be several of those things at once. The property doesn’t have to change for the question to change.
And before we start arguing about the answer, it’s probably worth making sure we’re all asking the same question.
Christopher Pyle has more than 20 years of real estate appraisal experience in Northern California. He works alongside his mother, longtime appraiser Christine Pyle Banks, at AppraiserChris.com, their family appraisal practice serving the Sacramento region and Sierra Nevada foothills. His work focuses on helping homeowners, families and professionals better understand property value and the decisions that surround it.